Re:Money
Five Checks That Keep a Coinsurance Clause From Trimming Your Claim, Debris Included
Dated5 min read
Rebuild costs moved, policy limits often did not, and the shortfall gets applied to the whole loss. Five checks, and the paperwork that settles each one.
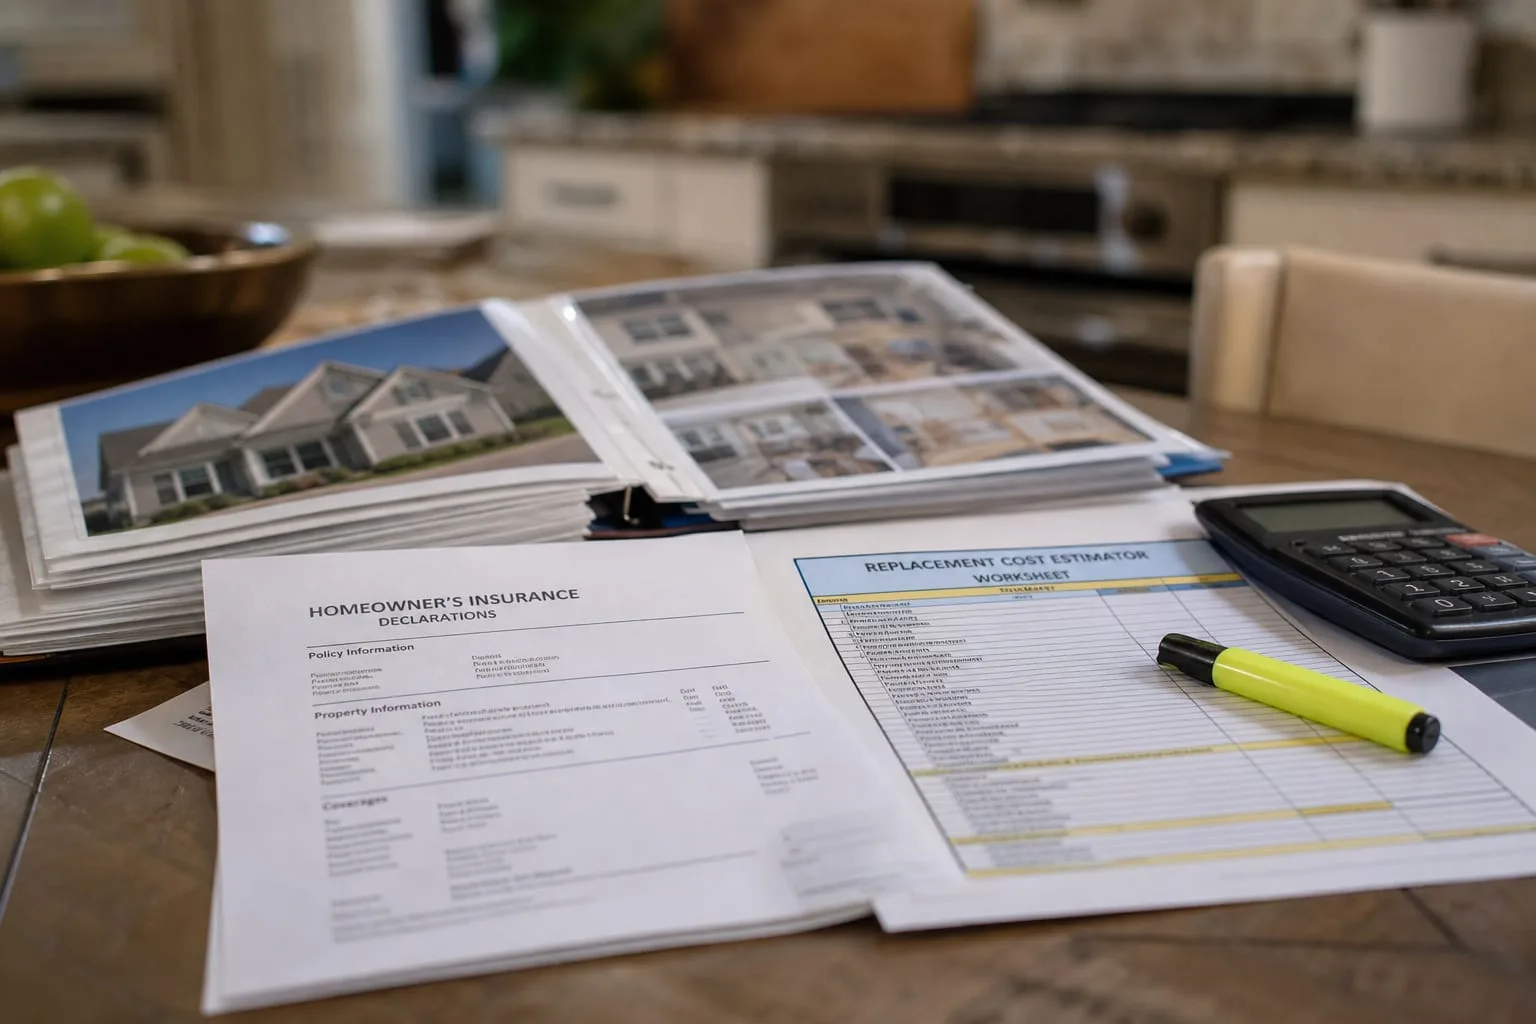
The number that decides whether a claim pays in full is not the one on the front of the policy. It is the relationship between that number and what a contractor would actually charge to put the building back, on today's labor rates, with today's material prices, and with today's disposal costs attached to hauling the old building away. When the first number falls short of the second by enough, the coinsurance condition engages and the payment is scaled down in proportion. The claim is not denied. It is trimmed, arithmetically, and the arithmetic is not negotiable once the loss has happened.
1. Ask where the rebuild figure came from, and get the worksheet
Most dwelling limits are produced by a replacement cost estimator, a piece of software the agent runs with inputs on square footage, exterior wall type, roof covering, foundation, number of bathrooms, and interior finish grade. The output is only as good as those inputs, and the inputs were often typed once, at binding, years ago. Request the worksheet in writing and read the finish grade line first, because a kitchen described as builder standard when it holds custom cabinetry and stone counters will understate the whole estimate. Correct the inputs, ask for a rerun, and keep both printouts in the same folder.
Two things on that sheet get missed with unusual regularity. Detached structures, a garage, a shed, a fence, sit under their own percentage of the dwelling limit rather than inside it, which means a low dwelling number quietly shrinks them too. Site conditions matter as well: a hillside lot, a narrow driveway, or a house that a crane cannot reach changes the real cost of reconstruction in ways the software will not infer. Write those conditions down and hand them to the agent so they appear somewhere in the file.
2. Find the debris removal sublimit before you need it
Nobody rebuilds on top of the wreckage. Before a single new stud goes up, the burned or soaked structure has to be demolished, sorted, loaded, hauled, weighed, and tipped, and every one of those steps is billed. Debris removal is usually covered not as its own pot of money but as a percentage of the covered loss, which is the detail that matters, because a scaled-down loss payment scales the debris allowance with it. On a total loss with a heavy structure, plaster, tile, masonry, dimensional lumber, the removal bill can be a serious line item.
Weight is what drives the price, and tipping fees are charged by the ton. Ask your agent whether the policy carries an additional amount for debris removal when the standard percentage is exhausted, since some forms include a stated extra sum and some do not. Then ask what happens to trees, fencing, and driveway rubble, which often sit under separate and much smaller allowances. Get the answers in an email rather than a phone call. That email is the cheapest piece of documentation in this entire exercise.
3. Check the coverage for what cannot legally go in the dumpster
A house built before the late 1970s may hold asbestos in floor tile, mastic, pipe insulation, and textured ceilings, plus lead-based paint on trim and siding. Once a demolition crew disturbs that material, it stops being construction debris and becomes regulated waste, handled by licensed abatement contractors, bagged, manifested, and taken to a facility that will accept it. The Environmental Protection Agency oversees how asbestos and lead materials are handled and disposed of during renovation and demolition, and the cost difference between a mixed load and a manifested abatement job is not small.
Standard property forms exclude pollution cleanup in broad terms while leaving a narrow allowance for testing and removal that shows up after a covered loss. Ordinance or law coverage is the endorsement that carries the weight here, because it responds to the code-required parts of the job: abatement mandated before demolition, the demolition of undamaged portions the building department will not let you keep, and the increased cost of rebuilding to current code. Confirm you have it, confirm the amount, and confirm whether demolition costs sit inside that amount or beside it.
4. Run the shortfall math yourself, on one page
The mechanism is simple enough to do with a calculator. Divide the limit you carry by the limit the policy requires, typically a stated percentage of full replacement cost, and apply that fraction to the loss. Carry less than required and you receive that fraction of the covered damage, less the deductible, on a fire that took out a kitchen or on a storm that took out a roof. The penalty does not wait for a total loss. Partial claims are where most people discover it, which is precisely why running the numbers on a hypothetical partial loss is the useful exercise.
The paperwork that heads this off is short. An inflation guard endorsement raises the limit automatically each renewal, extended replacement cost adds a stated cushion above the limit when construction prices spike after a widespread event, and an agreed value or waiver of coinsurance arrangement removes the penalty in exchange for an accepted valuation. Ask which of the three your carrier offers on your form, what each costs annually, and what documentation the underwriter wants in return, usually photographs, an updated square footage, and roof age.
5. Account for what has changed since the policy was written
Reconstruction pricing moved substantially through the early 2020s, and it moved unevenly: lumber, then labor, then everything downstream of freight. Disposal moved with it, as landfills tightened acceptance rules, separated loads became more common, and haulers repriced by weight rather than by container. Carriers responded by tightening underwriting, requiring exterior inspections and photographs, scheduling roofs onto actual cash value settlement past a certain age, and pushing revaluations at renewal. That last item is the useful one, because a revaluation letter is an invitation to correct the inputs you never checked.
Treat the renewal packet as a working document rather than a receipt. Read the declarations page against last year's, note every limit that changed and every one that did not, and query the ones that stayed flat while your county's building costs did not. Keep a folder with the estimator worksheet, the endorsement list, current photographs of each room, receipts for major improvements, and any correspondence about debris or code coverage. That folder is what turns a scaled payment into a full one, and it is assembled long before anything goes wrong.
The check is written against the paperwork that existed on the day of the loss, not the paperwork you meant to update. An hour with the worksheet and one email to the agent puts both in the same place.