Re:Careers
Going Self-Employed? Five Checks, and the Clerk Who Decides When You Get Paid
Dated4 min read
The paperwork of self-employment was built for other people's filing cabinets, and the accounts payable clerk you never meet sets the rhythm of your household.
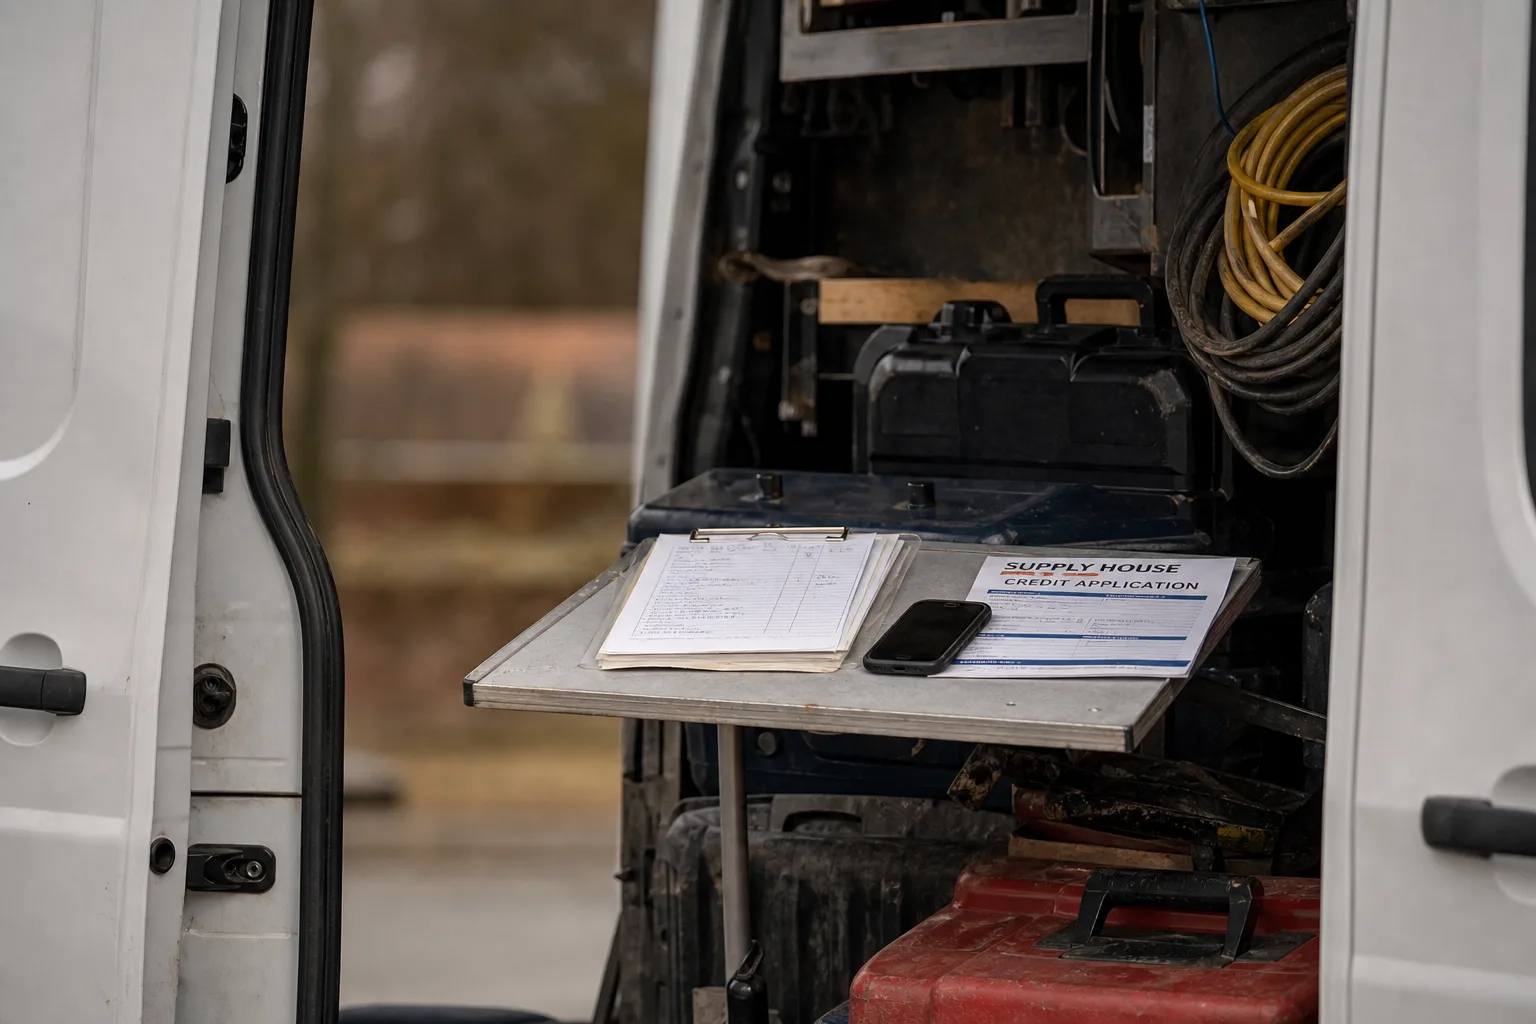
The first month on your own is usually not short of work. It is short of money, because the work and the money have come apart, and the gap between them is filled with paper that somebody else needs. A man who spent eleven years on someone's payroll has never seen a W-9, never chased a purchase order number, never had a check sit unsigned because the invoice lacked a job code. The tools are the same tools. The van is the same van. What changes is that a stranger in an office two towns over now sets the date your mortgage clears.
The forms you fill out exist because someone else has to file something
Almost every piece of paper you sign in your first year was designed for a filing cabinet that is not yours. The W-9 is collected so the client can issue a 1099-NEC in January, which they do because the IRS oversees how payments to non-employees are reported and matched. The certificate of insurance is collected so the client's own carrier does not come back at renewal and ask who was on the roof. The lien waiver is collected so a title company will release funds on a sale. None of it was built around your convenience, and once you see that, the requests stop feeling arbitrary and start feeling predictable.
That history matters because it tells you where to push and where not to bother. A general contractor who will not release a progress payment without a signed conditional waiver is not being difficult; his lender has told him the sequence. Get the forms ready before you need them, scanned and in one folder, and you remove the most common reason a payment sits.
The certificate of insurance is written for the client's file
General liability, and a commercial auto policy if the van is yours, are the two most trades buy first. What people miss is that the document that actually travels is the certificate, a one-page summary your agent issues naming the client as certificate holder, sometimes as additional insured. Larger clients will not let you on site without it, and some will not cut a check if it expired midway through the job. Ask your agent how fast they turn one around, and whether an additional insured endorsement costs extra, because that is the request that arrives at four on a Friday when the crew is due Monday.
The supply house counter is the second place you get hired
Trade credit is the quietest decision in the whole business. Open an account at the supply house, pass their credit check, and you get net thirty, which means the materials for a job are financed by the supplier until the client pays you. Buy the same pipe, lumber and fasteners on a card at a big box, and you are financing them yourself at whatever your interest rate happens to be. The counter staff also decide, informally, who gets the last four of something on a Tuesday morning when three crews want it. That relationship is worth protecting with the same care you give a client's.
Keep a written record of what you substitute and why. A different brand of flex connector, a different thickness of backer board, a different screw because the specified one is six weeks out. Clients rarely object at the time. They object later, when a punch list is being written and nobody remembers the conversation held in a kitchen with the cabinets out and a fan running.
The accounts payable clerk nobody introduces you to
This is the person most tradespeople never account for. The owner hired you, shook your hand, and may genuinely want you paid, but the check is cut by a bookkeeper or a controller who works to a run date, often twice a month, and who will not break the cycle for a one-page invoice that is missing a job number. Call the office before you invoice and ask three things: what the payment terms are, what the invoice must show, and when the check run happens. Thirty days from an invoice that lands the day after a run is forty-five days in practice, and a household can plan around forty-five if it knows.
The quarter becomes the unit your household runs on
Withholding used to happen to you. Now you do it, four times a year, out of money that is already in the account and already spoken for. The usual working method is a second checking account, a fixed percentage moved the day each deposit clears, and no exceptions in a slow month. Add a set-aside for the things that wear first, drill batteries, blades, tires, a replacement vacuum when the drywall dust finally kills one, because those costs arrive without warning and otherwise come out of the tax money. A household that knows which week the quarterly payment leaves plans its own six weeks without a kitchen around it.
The trade skill got you here. The administration is a separate skill, learned later and usually in public, and it runs on knowing which stranger in which office is holding your money and why. Find that person's name in the first week of every new client relationship. It will shorten everything that follows.