Re:Money
Worth Filing? Five Questions That Decide Whether to Claim or Pay It Yourself
Dated5 min read
Before you call the carrier about a damaged floor or a cracked pipe, five checks that tell you whether the claim is worth what it costs you at renewal.
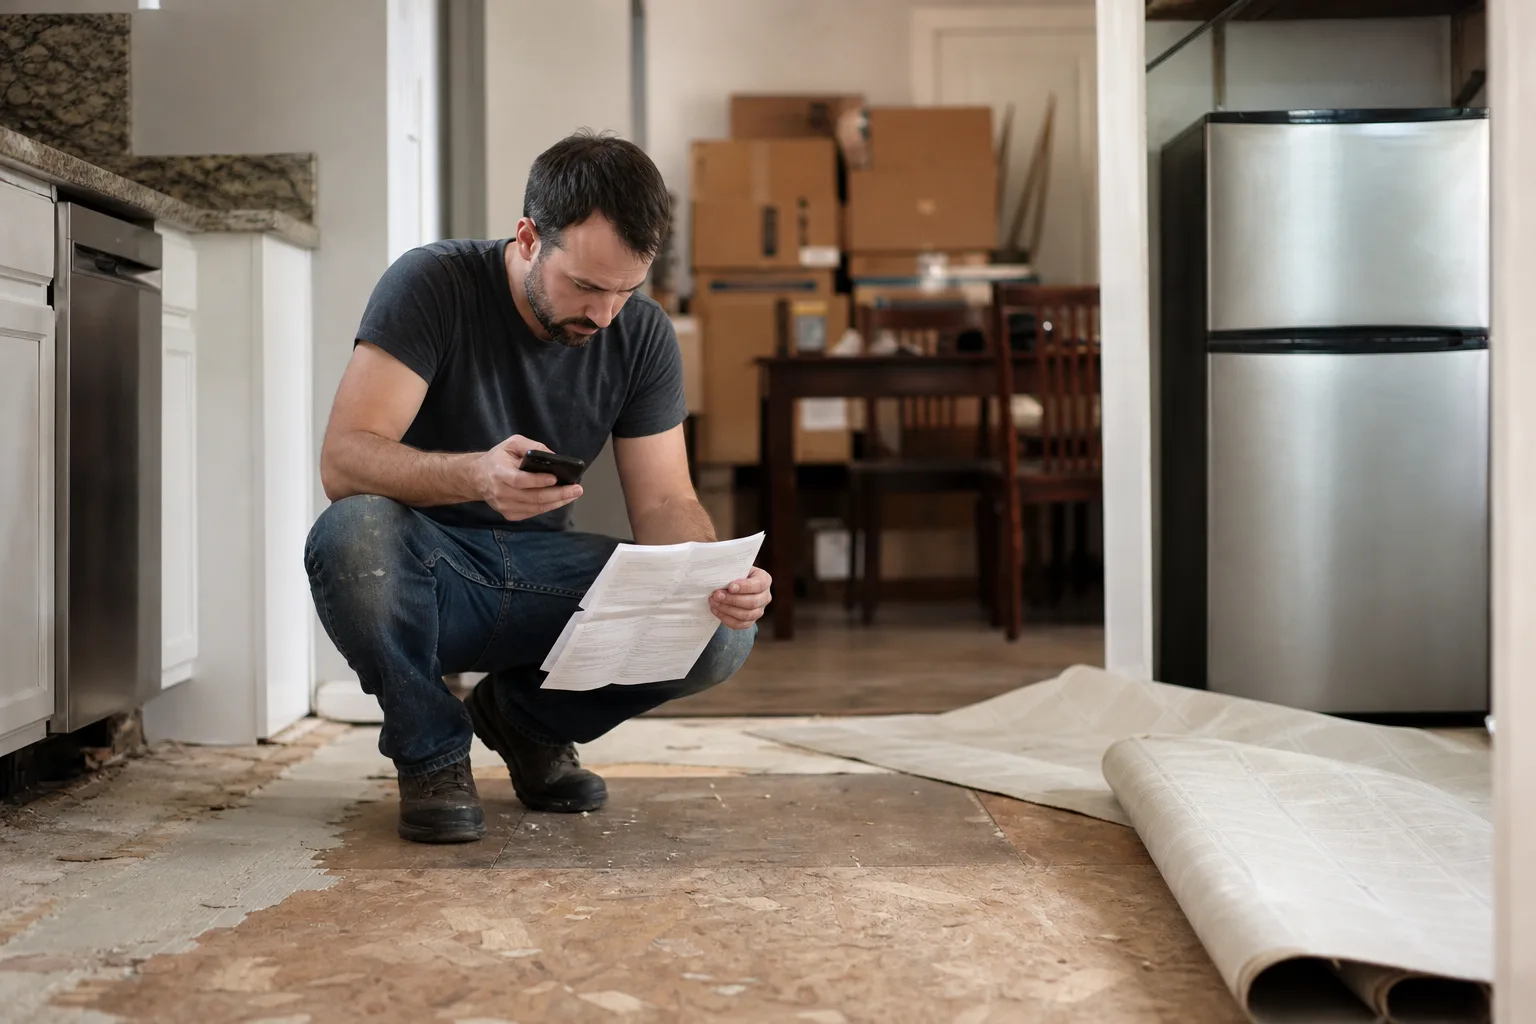
The moment that decides most of this happens on a weekday evening, standing on a wet subfloor with a flashlight, phone in hand, with the carrier's claims number already dialed and your thumb not quite on the green button. Nobody teaches the judgment involved. You are asked to weigh a check you can picture against a renewal premium you cannot, and to do it while the house smells of damp particleboard and the kids are asking where they are sleeping. The decision is not about honesty or nerve. It is arithmetic, plus a few facts about yourself that you can look up before you call.
What is the actual gap between the loss and your deductible?
A deductible is not the number that matters by itself; the number that matters is what the carrier would hand you after the deductible comes out, and that figure only exists once somebody has priced the repair. Get two written estimates first, from contractors who will put line items on paper: tear-out, haul-away, subfloor, underlayment, flooring, baseboard, paint, labor. A kitchen floor that looked like a four-figure problem often turns out to be a five-figure one once the cabinets have to come out and go back. If the gap after the deductible is small, you are trading a modest check for years of being a household with a claim on file.
The honest version of this calculation includes the parts nobody quotes. Six weeks without a kitchen means takeout, a hot plate in the dining room, a mini fridge borrowed from a neighbor. If your policy covers additional living expenses and the repair genuinely displaces you, that coverage can dwarf the repair itself and changes the math entirely. Price the displacement the way you priced the flooring. A loss that pays four thousand on paper may be worth far more once a hotel and a storage unit are counted, and that is exactly the loss worth filing.
What does your own claim history already say about you?
Carriers do not guess at your past. They pull a loss history report compiled from what insurers have reported, typically covering the last several years, and it shows the date, the type of loss, the amount paid and often the property address rather than just your name. You are entitled to see this file about yourself, and under the federal consumer reporting rules the Federal Trade Commission oversees, you can request a copy and dispute entries that are wrong. People do find errors: a claim logged against the wrong address, a loss recorded as paid when it was closed without payment, a prior owner's water damage attached to a house you bought later.
Read your file before you need it, not after. What you are looking for is pattern, because pattern is what underwriters price. One wind claim after a storm that took half the street's shingles reads very differently from a third water loss in five years, which reads to an underwriter as a plumbing system nobody has fixed. Knowing which story your file tells changes the decision in front of you tonight. A clean file absorbs one claim comfortably. A file with two water losses already on it means the third one has to be worth a great deal.
Does asking a question become a claim in the file?
This is the part households get wrong most often, and it is worth being careful rather than clever about it. Practice varies by carrier and by state, and a call that you intend as a general question about coverage can sometimes be logged as a notice of loss, which can appear in your history even if no money is ever paid. The safe approach is to be explicit. Say plainly that you are asking a coverage question about a hypothetical and are not reporting a loss, and ask directly whether the call will be recorded as a claim or an inquiry.
Better still, do the reading yourself first. Your declarations page gives you the deductible, the coverage limits and any separate wind or water deductible, and the policy form tells you what is excluded. An independent agent, if you have one, can talk through a scenario without touching the carrier's system, because the agent works between you and the company. Get the answer in writing where you can, by email rather than phone, so that six months later you know exactly what you were told and by whom.
What kind of loss is it, and what does that type predict?
Underwriters sort losses into causes, and the causes carry different weight. Weather losses that hit a whole neighborhood are treated as something that happened to you. Repeat water losses from supply lines, water heaters, washing machine hoses and failed shutoff valves are treated as something about the house, because they predict recurrence, and prediction is the whole business. Liability claims, somebody hurt on your property, sit in their own category and tend to be taken seriously regardless of the amount.
So the question is not only how much the loss is worth but what filing it tells your carrier about the next five years. A burst supply line under a sink, repaired properly with braided stainless replacements throughout the house and a photograph of each one, is a loss with a documented ending. Say so when you file. Adjusters write notes, those notes travel, and a file that shows the cause was found and eliminated is a far better file than one that shows a check and silence afterward.
What can you do between now and the renewal notice?
A claim does not have to be the last word you get in. Keep the contractor's invoices, the permit if one was pulled, the photographs of the new valves or the new roof deck, and keep them somewhere you will find them in eleven months. When the renewal arrives and the number has moved, you have something concrete to put in front of an underwriter or in front of a competing carrier's agent, which is a repair that removed the cause rather than a promise to be careful.
Then shop the policy on your own schedule, well before the renewal date, with your loss history report in hand so that nothing in it surprises you mid-quote. Carriers weigh the same file differently; one treats a single water loss as noise, another prices it hard. Ask about raising the deductible, since a household that has decided to absorb small losses should stop paying for coverage of small losses. That is the quiet benefit of having run these five checks once. The next time you are standing on a wet floor with the phone in your hand, you already know which way you are going.